
We might actually be seeing a payoff for the US Federal Reserve’s hardline fiscal tightening game plan.
Inflation fell to 7.7%, a good deal more than the 8% forecast, with core inflation – which excludes food and energy – falling to 6.3% against 6.5% expectations.
It’s still far above the Federal Reserve’s target of 2%, and the markets reacted with a huge relief rally on riskier equities products and a sharp sell off of the US dollar.
The US Dollar Index (DXY) plummeted 2.3% in yesterday’s session, and losses are continuing this morning, with the going rate at three-month lows of 107.31.
Following the softer inflation figures, three Fed speakers put their weight behind a looser economics policy going forward.
Today’s UK gross domestic product data showed a quarterly contraction of -0.2%, which was quite a bit less than the -0.5% expected and as such, yearly GDP grew above forecasts at a rate of 2.4%.
The trade deficit also tightened.
GBP/USD responded extremely well to this mix, surging nearly 3% to two-months highs of US$1.173 yesterday and continuing to rally this morning.
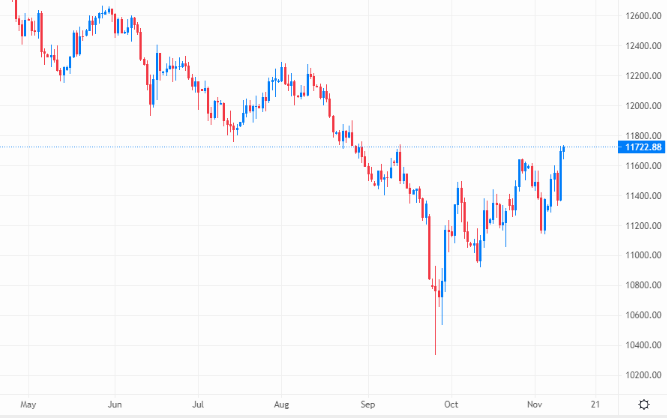
August highs are next in GBP/USD’s sights – Source: capital.com
Cable has so far held those September highs and is eyeing up the US$1.19 resistance level.
EUR/USD has already exceeded August highs after soaring to US$1.02 yesterday and continuing to surge to US$1.023 in this morning’s Asia trading hours.
Plenty of resistance has been clocked at the US$1.03 price point.
EUR/GBP lost around 100 pips yesterday but there are signs of clawbacks this morning as traders hunt down riskier equities options. The pair is currently changing hands at 87.19p.