
- FTSE 100 finishes 0.12% higher
- US markets closed for President's Day
- House prices stabilise in February - Rightmove
4:40pm: FTSE sees positive end to twiddling day
The FTSE 100 ended a ‘thumb-twiddling’ day holding above 8,000, with the market described as direction-less this afternoon as North American remained closed for the public holiday.
At 8,014, the London benchmark was up around 10 points or 0.12%.
“what little risk appetite there is has ebbed away this afternoon,” IG Markets analyst Chris Beauchamp said in a note.
“Earlier gains for European indices have been chipped away this afternoon, as concerns about interest rates and the ongoing Ukraine conflict sapped risk appetite.”
“The past month has seen a dramatic repricing of expectations around interest rates.
“Previously, markets had seen cautiously optimistic that the end of the surge to tighten rates was upon us. Stronger data from various quarters has reversed that view entirely.”
4.10pm: Every little helps
Tesco has said it will raise hourly pay for about 220,000 store workers by 7% from April.
Britain's biggest retailer, one of the country's largest private sector employers, said a deal agreed with shopworkers union USDAW will see store workers get £11.02 an hour from April 2, 2023, up from £10.30 currently. Workers in inner and outer London will get additional allowances.
Tesco said it will also continue to provide staff with free food in-store canteens, a salary advance scheme and a discount of up to £1,500 a year off their shopping.
The supermarket group said the wage increase, the third in ten months, will cost it over £230mln and take investment in pay over the last year to £430mln.
3.55pm: NatWest clipped
Barclays Capital has cut its near-term earnings estimate for Natwest Group PLC following lower pre-provision profits but has lifted outer years slightly on lower impairments.
The UK clearing bank's current-year revenue guidance of £14.8bn appears underpinned by a number of conservative assumptions, which suggest upside potential, the research note said.
However, the outlook for deposits has emerged as a key area of uncertainty following fourth quarter outflows sooner than expected, rising deposit betas and mix shift, it said.
Barclays Capital sees Natwest's potential deposit outflows as potentially more significant than peers, it said.
3.35pm: Costs going nuclear
EDF's new nuclear plant in southwest England is likely to cost about 2% more than its last budget estimate as inflation propels the price tag to almost £33bn ($40bn), documents from the French power firm show, according to a Reuters report.
Britain plans to build new nuclear plants to boost its energy security and help meet a target for net zero emissions by 2050.
EDF warned in a results presentation on Friday the cost of the Hinkley Point C project, Britain's first new nuclear plant in more than two decades, "could reach 32.7 billion pounds" based on inflation indexes as of June 30, 2022.
Its previously published cost estimate in May 2022 was 31bn-32bn euros when adjusted for inflation, Reuters noted.
3.10pm: Woodford settlement talks with Link at 'advanced stage': regulator
The Financial Conducts Authority (FCA) has said that talks are at an advanced stage between itself and share registrar, the Link Group to draw a line under the Woodford Investment Management scandal.
In a statement, the UK regulator said: “We are in advanced confidential discussions with Link Group and LFS to determine whether the FCA’s proposed enforcement action against LFS can be resolved by agreement.
“The FCA is focused on ensuring that consumers affected by the suspension of the Woodford Equity Income Fund (WEIF) obtain redress. To assist a potential resolution, the FCA has provided time for Link Group to realise assets, including Link Group held assets, to meet the FCA’s concerns.”
Australian group Link's UK arm was cited by the FCA for its part in the collapse of the Woodford Equity Income fund in 2019, which closed after being unable to meet a run of redemption requests due to the illiquidity of its assets.
In a preliminary ruling last September, the FCA said it was fining Link Financial Solutions (LFS) £50mln and up to a further £306mln for possible redress as a result of its “failings in managing the liquidity of the WEIF”.
2.40pm: DS Smith rating folded
Analysts at BofA Merrill Lynch have cut their rating for packaging company DS Smith PLC to 'neutral' from 'buy' as they expect the group to see much lower box volumes in the third quarter and for prices to fall in 2024.
The US bank's analysts reckon that volumes are past their peak and expects them to drop as a result of de-stocking. They also pointed to higher energy and labour costs.
The analysts noted that DS Smith's peers have reported "relatively strong de-stocking effects in container-board/boxes" this earnings season.
They concluded that the FTSE 100-listed shares appear "fairly priced" and have outperformed peers by 10%-15% over the last three months. In afternoon trading, DS Smith shares were down 4.4% at 337.80p.
2.25pm: Power of the Dog
Craft beer firm BrewDog is expanding its operations in China, after signing a partnership with brewing giant Budweiser which will see a further nine Brewdog bars opened in China, adding to one it already has trading in Shanghai.
Privately owned Brewdog already has a small production line in China, which brewed 6.5mln hectolitres in 2020, out of a total 341mln hectolitres made collectively across the country.
China accounts for just 1% of Brewdog’s global sales currently, with the new partnership aiming to up its stake in the country's market, which has grown over the past decade to become the world’s largest producer and consumer of beer.
Brewdog, which was founded in Scotland in 2007, partnered with Japanese brewer Asahi in 2021 as part of its bid to expand into the Asian market, with the new deal also set to boost operations in South Korea.
2.10pm: Lacking direction
The FTSE 100 index edged higher in early afternoon trading, holding above the 8,000 level but failing to move much in the absence of any US lead today, with Wall Street closed for the President's Day public holiday.
Around 2.10pm, the UK blue-chip index was up 13 points, or 0.2%, at 8,017, just below the session peak of 8,018.56, having only reached a low of 8,004.36.
Craig Erlam, senior market analyst, UK & EMEA, OANDA commented: "Stock markets in Europe are treading water in thin trade at the start of the week amid a light economic calendar and a US bank holiday.
"It was always likely to be a slow day under the circumstances and that's exactly what it's turning out to be. Stock markets remain in a surprisingly strong position despite the uncertain outlook and rising interest rate expectations due to stubborn inflation.
"While other areas of the market appear to have adopted a more defensive position, equity investors remain undeterred. It would appear it's going to take a lot more than a few nasty economic releases to put a dent in their optimism."
1.30pm: A quick look at some of today's risers and fallers
Pineapple Power - up 49% to 3.7p: The cash shell announced that Graham Cooley, the former chief executive of hydrogen electrolyser pioneer ITM Power, has joined its advisory board. Cooley, who stepped down from ITM in September, joined it in 2009 shortly after which it became the first hydrogen-related company to be listed on the London Stock Exchange.
Proteome - up 31% to 4.92p: Shares spiked after it said revenues last year grew by more than half, while its cash position improved markedly too. In a trading update, the group, a specialist provider of contract proteomics services used in drug discovery, said turnover for the 12 months ended 31 December 2022 increased by 53% to around £7.8mln.
Upland Resources - up 13% to 0.6p: Upland's shares moved sharply higher on Monday as the explorer announced that cornerstone investors would provide a £1.25mln injection of capital into the company. Investors committed to subscribe for 208.3mln new shares in the company at a premium price of 0.6p per share
Verditek - down 17% to 0.6p: Shares plummeted after the UK clean technology firm revealed its distribution agreement with Bradclad has been terminated. The move followed a lack of new orders since June 2022 and an announcement in October stating that Bradclad was engaging with another manufacturer.
Tekcapital - down 16% to 17p: Shares moved lower in Monday morning’s deals, pricing in equity dilution from its latest share placing. The investment firm said it would be issuing 14mln new shares priced at 16p each to raise £2.25mln of new capital in a placing arranged by stockbroker SP Angel.
1.00pm: Virgin Media eyeing bid for Trooli - Sky
Virgin Media O2 and its shareholders are exploring a takeover bid for Trooli, one of the UK's army of 'altnet' fibre broadband companies, according to a report.
Sky News has learnt that the telecoms giant, which is jointly owned by Liberty Global (NASDAQ:LBTYA) and Spain's Telefonica, is among a substantial number of parties examining offers for Trooli as part of a formal auction process.
Telecoms industry sources said any offer was likely to be worth in excess of £100mln.
Trooli is exploring a sale amid growing pressure on the deluge of alternative network - or altnet - providers which have sprung up in the last decade as part of efforts to transform Britain's communications infrastructure.
The market is dominated by BT Group's Openreach division, but also includes large competitors such as CityFibre Holdings.
Meanwhile, big news is that the FTSE 100 has moved from up 1 point to down 1 point at 8,003 as it remains subdued to say the least.
12.20pm: German economic outlook brightens, inflation pressures remain
Germany’s economic prospects are improving, the country’s central bank believes, as energy prices ease and the global economy picks up.
In its latest monthly report, the Bundesbank said that the economic outlook for Germany was “somewhat brighter”, despite persistently high inflationary pressures.
It predicted that the end of the zero-Covid policy in China is likely to pave the way for a global economic recovery.
Bundesbank: Headline inflation has peaked in Germanyhttps://t.co/3vsLXxHzlQ
— ForexLive (@ForexLive) February 20, 2023
“The global economy continued to see only moderate growth in the final quarter of 2022 owing to various headwinds. The main factors behind this slowdown were high inflation rates, the continued tightening of monetary policy in many industrial countries and the European energy crisis due to Russia’s war on Ukraine.
“At the turn of the year, sentiment amongst entrepreneurs and consumers worldwide brightened slightly, with recessionary fears receding somewhat. This is likely to have been helped by the distinct easing of the European energy crisis,” the German central bank said.
Germany’s economy shrank by 0.2% in the final quarter of last year, a smaller fall than expected.
The Bundesbank said that the fall was “milder than anticipated”, thanks to easing supply chain problems and the fall in European energy prices, which hit 18-month lows last week.
11.45am: Household energy bills set to fall
Household energy bills are on course to be 13% lower in July as the price cap is expected to drop to £2,165 per year.
The estimate by Investec, reported in the Telegraph, is more than £300 below the government's £2,500 energy price guarantee in force at present.
It will be more than £800 lower than what consumers will pay from April once the guarantee lifts to £3,000.
It comes as European natural gas prices have fallen to their lowest levels in 18 months after a mild winter meant storage levels have remained high across the continent.
Household energy bills should stabilise later in the year, with the price cap rising modestly to £2,190 from October. Investec's final estimate for the price cap in April is £3,332.
It means the Government will pay £332 per household to cover its annual average energy bill from that point as it caps the price paid at £3,000, up from its present cap of £2,500.
Little to report on the Footsie which for now remains stuck in a tight range around its opening levels.
11.10am: European construction sector fell in December - Eurostat
Europe’s construction sector contracted at the end of last year, new figures from Eurostat showed.
Production across the eurozone’s construction sector dipped by 2.5% month-on-month in December, and was down 2% in the wider European Union.
Euro area (EA19) #construction down by 2.5% in December 2022 over November, -1.3% over December 2021 https://t.co/TvHpSsu6qp pic.twitter.com/EZholhqOPB
— EU_Eurostat (@EU_Eurostat) February 20, 2023
Year-on-year, construction production was down 1.3% in the euro area and by 0.4% in the EU.
Claus Vistesen chief eurozone economist at Pantheon Macroeconomics said the fall was mainly due "to a sharp decline in Germany, where production plunged by 8.0% on the month, due to an unusually higher number of frost days."
Back in London and it remains a lacklustre session. The FTSE 100 is currently at 8,003.13, down 1.23 points.
10.35am: Lloyds, Virgin Money and NatWest possible buyers for Tesco Bank
Offloading Tesco’s banking arm “makes perfect sense,” according to AJ Bell investment director Russ Mould.
“Tesco is likely to be more interested in improving its supermarket experience and delivery capabilities than expand a banking business. With Aldi and Lidl snapping at its heels, it makes sense to streamline now," he said.
Mould pointed out Tesco Bank has more than 5mln customers which "means it could be an attractive acquisition for another banking provider seeking to grow their market share.”
He highlighted Lloyds Banking Group PLC (LSE:LLOY), Virgin Money PLC and NatWest PLC as possible suitors.
Mould was responding to a report on Sky News which suggested Britain’s largest food retailer was looking at selling Tesco Bank and has lined up Goldman Sachs (NYSE:GS) to advise on the deal.
Mould said: “We’re in an era where companies are focusing on what they do best, rather than trying to stretch themselves too thin by doing too much.
“We’ve seen numerous demergers in recent years as companies streamline to have a sharper focus and unlock hidden value in their business.”
“With that backdrop in mind, one should expect to see many companies like Tesco concentrate on what they do best and find someone else to take over activities on the periphery.
“The days of consumer-facing companies offering a broad range of services to their customer base are long gone.
"Banking is a heavily regulated business and staff must keep on top of a lot of rules and complexity. The broader financial services space is highly competitive and requires significant investment in technology to improve systems," he added.
But Mould noted that given Sainsbury’s had put its banking unit up for sale and “then decided to keep it might suggest there is a big difference between what it thought the business was worth and what someone else is prepared to pay.”
“Might the same apply to Tesco,” he asked.
10.00am: Aldi expanding but retail sector shedding jobs overall
Mixed news on the jobs front in the UK retail sales sector.
Aldi, the German discount retailer, plans to almost double its 60-strong store estate in London, according to Reuters.
Aldi UK's overall store target is 1,200 by 2025. It invested £700mln in 2022 and plans to invest £600mln in 2023.
Last week it said it would create over 6,000 jobs this year.
But a report from the Centre for Retail Research showed nearly 15,000 British retail jobs have already been cut since January in a “brutal start to the year” for the high street.
A total of 14,874 retail job losses have been announced by companies so far, the report said.
National retailers including stationery brand Paperchase, clothing chain M&Co and Tile Giant have all gone bust in recent weeks, while discount retailer Wilko, clothing retailer New Look and supermarkets Tesco and Asda have all also announced job cuts.
9.30am: Oil price rallies
Oil prices rose on Monday after falling 4.3% last week on concerns over higher interest rates in the US.
Fiona Cincotta, senior financial markets analyst at City Index said “the risk on mood at the start of the week is helping risk assets, such as oil push high.”
“Optimism surrounding the reopening in China is also keeping oil prices supported. The EIA and OPEC have highlighted Chinese demand as a key river of demand growth this year," she added.
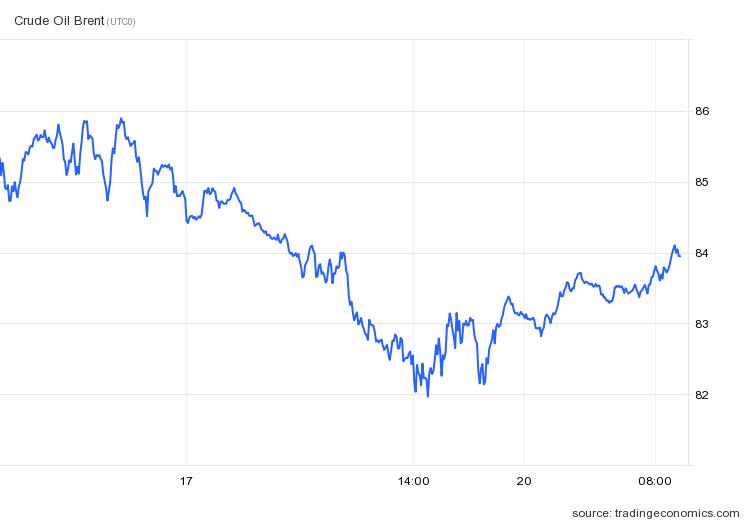
Brent crude rose 1.2% to US$83.94 a barrel, while West Texas Intermediate crude was priced at US$77.14 a barrel, up 1.1%.
The rise helped underpin BP PLC (LSE:BP.) shares, up 0.3%, although Shell PLC (LSE:SHEL, NYSE:SHEL) was little changed.
09.00am: Footsie edges higher
The FTSE 100 has made steady early progress in early exchanges, now at 8,016.20, up 11.84, or 0.15% but activity may be quiet with US markets closed for President’s Day.
Richard Hunter, Head of Markets at interactive investor noted: “The index remains protected by its mixture of defensive, higher-yielding shares, with additional exposure to banks which are seeing the benefit of rising interest rates and mineral stocks which are poised to pounce on recovering demand from China as the year progresses.”
Frasers Group PLC (LSE:FRAS) remained top of the FTSE 100 risers, up 3.4%, after launching a £80mln share buy-back and lenders Barclays PLC (LSE:BARC) and Lloyds Banking Group PLC (LSE:LLOY) recovered some of the ground lost last week in the wake of disappointing earnings updates in the banking sector. But NatWest Group PLC (LSE:NWG) fell further, down 1.4%, on further consideration of its results last Friday.
Persimmon PLC (LSE:PSN), Taylor Wimpey PLC (LSE:TW.) and Barratt Developments PLC (LSE:BDEV) all rose after the latest Rightmove house price index figures which showed house prices were little changed in February.
Recent surveys had shown falling prices as rising mortgage rates and worries of an economic downturn had hit the market.
Elsewhere Keystone Law shares advanced 8.1% after reporting "favourable market conditions" continued in its financial second half ended January 31, 2023.
Client demand "remained robust", the law firm said. It said annual revenue and adjusted pre-tax profit will now top current market expectations.
But on the downside was AIM-listed Verditek which dropped 28%. The solar panels producer said it has received a notice for its distribution agreement with partner Bradclad Group to be terminated.
8.15am: FTSE steady at the start
The FTSE 100 opened little changed on Monday holding above the psychologically important 8,000 level.
At 8.15am, London’s lead index was at 8,004.47, up 0.11%, while the FTSE 250 rose 19.23 points to 20,108.16, up 0.09%.
Susannah Streeter, head of money and markets, Hargreaves Lansdown said: “There’s a quiet pulse of positivity on the markets with investors still cautious about the direction of interest rates in the United States, but hopeful that recovery elsewhere will lend a hand to trade.”
But she noted: “Volumes are set to be more muted during the sessions in Europe given that Wall Street is closed for the President’s Day holiday, so traders are likely to be searching around for a bit of a sense of direction today, looking ahead to fresh data out this week.”
The data includes the release of the minutes of the last Federal Open Market Committee meeting due out on Wednesday.
Markets in China and Hong Kong rose following the announcement of unchanged prime loan rates in China.
Back in London, Frasers Group PLC (LSE:FRAS) jumped 3.4% after the retailer started a £80mln share buy-back.
Tesco PLC (LSE:TSCO) gained 0.4% on reports the grocer was considering the sale of its banking arm.
Sky News reported Britain’s largest food retailer has lined up Goldman Sachs (NYSE:GS) to advise on the future of Tesco Bank, which launched in 1997.
The report said Tesco Bank could be worth more than £1bn based on its book value if sold.
But Trifast (LSE:TRI) PLC plunged 41% after it warned profits would be significantly below current market expectations and that its boss had quit.
While full-year revenues are seen little changed adjusted pre-tax profits are forecast to tumble to around £9mln, down from previous guidance £14.3mln.
“We have continued to see macro-economic conditions contribute to some volatility in demand patterns, and in particular have, more recently, been impacted by significant destocking from one of our Asian manufacturing customers,” Trifast (LSE:TRI) said in a statement.
The warning was accompanied by news chief executive Mark Belton had resigned on Saturday replaced on an interim basis by non-executive director, Scott Mac Meekin.
Darktrace PLC (LSE:DARK) rose 1.5% after it appointed Ernst & Young to provide an independent third-party review of its key financial processes and controls.
The embattled cybersecurity firm has been accused of irregular sales, marketing and accounting practices raised by US-based hedge fund Quintessential Capital Management.
"The board and management are confident that Darktrace's independently audited public company financial statements fairly represent Darktrace's financial position and results," the company said on Monday.
Earlier this month chief executive Poppy Gustafsson published a strong defence of the company after its share price collapsed to a record low after the publication of a highly critical report by New York-based QCM.
7.40am: UK house prices little changed in February according to Rightmove
UK house prices were largely unchanged in February, figures from Rightmove PLC (LSE:RMV) showed on Monday, in a sign of buyer confidence despite robust mortgage rates.
The online real estate company said the average price of properties coming on the market was £362,452 little changed from £362,438 in January.
The online property website said it was the smallest February increase on record but the reading "could be seen as a positive indicator for the year ahead".
"This month's flat average asking price indicates that many sellers are breaking with tradition and showing unseasonal initial pricing restraint. In addition to market conditions demanding greater realism on price, we are transitioning into a slower-paced market, where buyers will take longer to find the right property at the right price due to the higher cost of servicing a mortgage," Rightmove analyst Tim Bannister said.
7.25am: Tesco exploring sale of Tesco Bank - Sky
Tesco PLC (LSE:TSCO), Britain's biggest supermarket chain, is to kick off a review of its presence in the UK banking sector - a move that could lead to a sale of the business, according to a report.
Sky News has learnt that the grocery giant is lining up Goldman Sachs (NYSE:GS) to advise on the future of Tesco Bank, which launched in 1997.
City insiders said this weekend that the review was at a very preliminary stage and may not lead to a formal sale process.
Exclusive: Tesco, Britain’s biggest retailer, is to kick off a review of its presence in the financial services sector that could lead to a sale of the banking arm it launched in 1997. Goldman Sachs (NYSE:GS) is being lined up to advise Tesco on the situation. https://t.co/3anaC1k0OJ
— Mark Kleinman (@MarkKleinmanSky) February 18, 2023
One source suggested that a partial sale or joint venture could also be an option for the retailer.
A banking analyst suggested this weekend that if it was sold, Tesco Bank could be worth more than £1bn based on its book value.
The company has more than 5mln customers, offering products including pet insurance, savings accounts and credit cards.
Ken Murphy, who has been Tesco's chief executive since 2020, has been publicly supportive of its presence in the banking sector.
7.20am: Harland & Woolf wins new deals
Harland & Wolff Group Holdings PLC (AIM:HARL) has secured contracts worth over £10mln within the defence, cruise & ferry and commercial fabrication markets.
The Belfast-based shipbuilder said the six contracts are expected to be completed during the next 12-18 months.
The AIM-listed firm did not disclose further details, due to confidentiality terms, but said that work on four of the contracts will commence this month in Belfast.
These contracts will involve fabricating a drydock gate for a client that operates a defence facility, repairs on a jack-up barge that is used for installation of offshore structures, as well as regular repair works on five vessels comprising a product tanker and four ferries.
In Arnish, the company has been contracted to undertake additional fabrication works for an ongoing mining project while it has been contracted to fabricate a frame at its Appledore facility for a prime contractor as part of its ongoing defence programme.
Harland & Wolff chief executive John Wood said: “Since the commencement of 2023, we are seeing an uptick in the level of enquiries flowing through all the yards for multiple projects.”
7.00am: Firm start seen by Footsie
The FTSE 100 is expected to open back above 8,000 on what could be a quiet day with little in the way of company and economic news expected and with US markets closed for President’s Day.
Spread betting companies are calling the lead index up by around 16 points.
“Today looks set to see markets in Europe open modestly higher against a backdrop of continued weakness in energy prices, which is relieving some of the worst-case economic scenarios that were being modelled at the end of last year. It's also likely to be a relatively subdued session given the absence of the US due to the President’s Day holiday,” commented CMC’s Michael Hewson.
In Asia, the People's Bank of China left its benchmark lending rate unchanged, an outcome in line with market expectations.
The move provided support to the Shanghai Composite which was up 2.0% in late trade while the Hang Seng climbed 1.1% in Hong Kong. In Tokyo, the Nikkei 225 edged up 0.1% on Monday. The S&P/ASX 200 in Sydney also climbed 0.1%.
US markets ended mixed on Friday with the Dow Jones Industrials Average up 130 points, 0.4%, at 33,827, the Nasdaq Composite down 66 points, 0.6%, to 11,787 while the S&P 500 shed 11 points, 0.3%, to 4,079.
Comments by a number of Federal Reserve officials forecasting further interest rates rises unsettled investors who had hoped that cooling inflation would prompt a pivot in Fed policy.
A quiet day for company news in London is expected on Monday ahead of a busy week with Lloyds, HSBC, International Consolidated Airlines, Rolls-Royce, and BAE Systems among the firms reporting.